
Structural adhesives
The global structural adhesives market grew to USD ~18.3 billion in 2016 with the CAGR of ~7.9% from 2016 to 2022.
High demand for lightweight metals and composites in applications such as automotive, transportation, building and construction and furniture are expected to fuel continued demand of structural adhesives.
Increasing government spending in public infrastructure and commercial buildings is likely to drive the demand for structural adhesive in construction applications such as window panels, roofing, and wall coverings. Changing consumer lifestyle with changing trends in furniture designs for building and construction applications is also likely to boost demand. However, fluctuation in raw material prices and strict environmental regulations may hamper the market.
Structural adhesive used in automotive can provide better adhesion between distinct substrates such as steel and plastics. These composites are used in doors, window glass attachments, brakes and clutch plates and so on. High demand for passenger cars in countries such as China and India, is expected to impact on market growth.
Water based structural adhesive are largely used in rigid joining such as furniture panels, automotive assembly, joint cements and household appliances. Stringent regulations regarding the presence of volatile organic compound (VOC) in solvent based adhesives has positively impacted on this market.
The structural adhesive market is segmented into product types such as epoxy, acrylic, cyanoacrylate, urethanes and others:
- Urethane adhesive are lower cost and are preferable with respect to elastic bonding in applications such as automotive and construction.
- Cyanoacrylic adhesives are expected to see high growth due to their low toxicity and faster setting.
- Epoxy adhesives provide high strength and temperature resistance which enhance the rigidity and reduce noise of automotive components such as turbines and blades.
Asia Pacific accounts for the largest market share due to rapid industrialisation and growing demand from the construction and furniture industries. China, India, Thailand and Indonesia are the fastest growing regions due to government tax incentives, subsidies and easy availability of raw materials and labour. North America is expected to see limited growth due to the slow growth of industries post-recession.
The key players in this segment are 3M Company, The Dow Chemical Company, Ashland Inc., SIKA AG, Henkel AG & Co., Lord Corporation, Scott Bader Company, Arkema S.A., Hubei Huitian Adhesive Enterprise Co., Ried B.V. Co. and others.
[edit] Find out more
[edit] Related articles on Designing Buildings Wiki
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Changing expectations around competence and compliance
New information sheet from CIAT.
Grenfell investigation files passed to CPS
Angela Rayner apologises on behalf of the British state.
Electrical contractors need to understand the practical implications.
The real barrier to getting more value from digital technology.
Your guide to The Construction Reset at UKCW Birmingham.
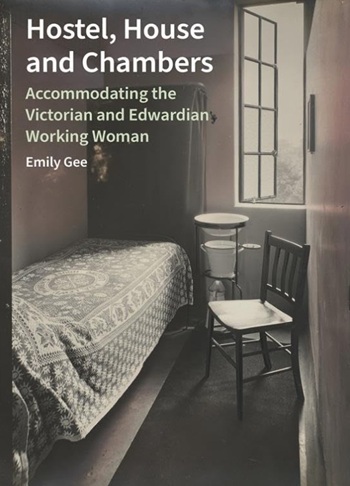
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
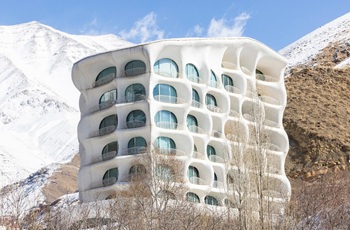
Shortlist for CIOB’s Art of Building photography competition.
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
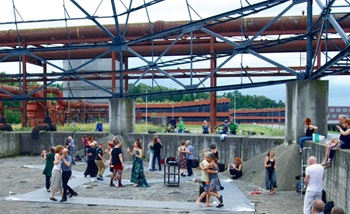
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.